Kim Anthony • July 10, 2026

Landmark Legislation Would Accelerate Preservation of Nation’s Aging Affordable Housing
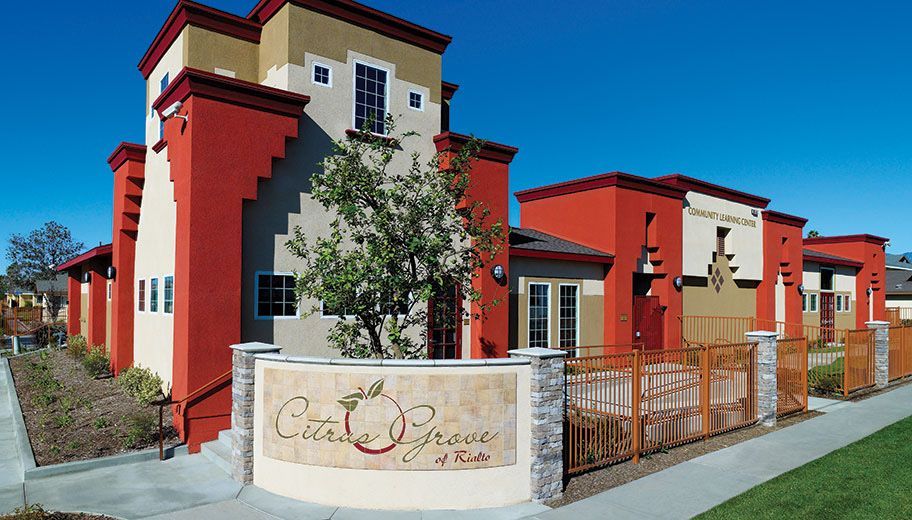
(Photo: National CORE)

RANCHO CUCAMONGA, Calif. — National CORE is applauding newly introduced federal legislation that would establish a new tax framework designed to preserve America's aging affordable housing while encouraging long-term private investment in rehabilitation projects.


Introduced on July 2 by U.S. Representative Mike Carey (R-Ohio), the Housing Opportunities and Preservation (HOPE) Act seeks to create new funding mechanisms to help preserve and rehabilitate existing affordable rental housing across the country.


The proposal comes as the nation faces a significant affordable housing shortage. According to the National Low Income Housing Coalition, the United States is currently short 7.2 million affordable and available rental homes for extremely low-income households. At the same time, the average federally assisted rental property is now 36 years old, and nearly 375,000 affordable homes are projected to lose their affordability protections over the next five years.


"The HOPE Act would unlock a major new private funding source for preserving our aging housing stock," said Mike Ruane, President of National CORE. "It's an innovative approach to one of the biggest challenges in affordable housing—ensuring today's affordable homes remain available for future generations."


Housing advocates across the country have increasingly emphasized that preserving existing affordable housing must be a central component of any comprehensive strategy to address the nation's housing crisis.


Over the past year, National CORE has worked alongside Novogradac & Company and a broad coalition of affordable housing organizations to explore innovative financing strategies that support long-term housing preservation.


The coalition includes nonprofit housing developers, preservation advocates, and affordable housing finance experts committed to strengthening the tools available to protect affordable housing for decades to come.


Preserving existing affordable housing is often significantly less expensive than replacing it with new construction. It also helps prevent resident displacement while preserving stable neighborhoods. Despite its importance, however, affordable housing preservation has historically lacked dedicated federal financing tools capable of meeting the growing need.


The HOPE Act seeks to change that.


The legislation would encourage greater private investment by creating a new federal tax framework for qualified affordable housing preservation projects. The proposal includes incentives designed to reward long-term rehabilitation investments while maintaining affordability for low-income residents.


To qualify, properties must:


  • Be owned by a qualified nonprofit organization, public housing agency, state or local government, or tribal housing agency;
  • Be at least 15 years old;
  • Undergo substantial rehabilitation; and
  • Remain affordable to low-income households for a minimum of 20 years.

"While Congress' permanent expansion of the Low-Income Housing Tax Credit last year was historic and critically important for affordable rental housing, particularly new construction, the nation's preservation needs extend well beyond those resources," said Michael Novogradac, Managing Partner of Novogradac & Company. "This legislation provides nonprofit housing owners with a flexible financing tool designed to attract individual investors while complementing—not replacing—the expanded housing tax credit."

Affordable housing leaders say the legislation would also help nonprofit organizations renovate more aging properties while ensuring long-term affordability.

"We need to preserve existing homes so low-income seniors, working families, and people with disabilities can continue living in quality affordable housing without being displaced," said Aaron Gornstein,

President and CEO of POAH. "The HOPE Act will expand private-sector investment, enabling nonprofit organizations to renovate more affordable homes while committing to long-term affordability."

The HOPE Act has been referred to the House Ways and Means Committee, where Rep. Carey serves as a member.
By Kim Anthony • September 25, 2026
Beginning January 1, 2027, California sales and use tax will generally apply to prewritten software delivered electronically or accessed remotely, including many Software-as-a-Service subscriptions. CALIFORNIA — If your business sells software, provides access to an online platform or pays for software subscriptions, a tax change belongs on your 2027 planning list. Under Senate Bill 122 , signed into law June 29, 2026, California is expanding the sales and use tax definition of tangible personal property to include certain digital products and associated copyright or patent interests. That means retail sales of covered products in California—and covered products purchased from a retailer for storage, use or other consumption in California—may be taxable beginning January 1, 2027 . The change generally affects sellers of prewritten software, SaaS providers, businesses that license or provide remote access to prewritten software, and the customers who buy those products. What counts as a digital product? For this law, a digital product is prewritten computer software delivered on physical storage media, transferred electronically or accessed remotely. Prewritten software is software held for general or repeated sale or lease. It can qualify even if it was originally developed for a particular customer or for a company’s own use. A combination of two or more prewritten programs can also qualify. What is outside this definition? The law does not classify every digital purchase as a taxable digital product. The following are excluded from its digital product definition: Digital assets, such as cryptocurrency Digital audio works, such as music, spoken recordings and ringtones Digital audiovisual works, such as movies and videos with sound Digital books, or eBooks Digital infrastructure, such as cloud platforms customers use to create, deploy or run their own software applications Digital video game products Digital visual works, such as computer-generated artwork The law also provides exemptions for custom computer software , digital products representing a service other than SaaS, digital products transferred with reproduction and distribution rights, and digital products purchased solely for use outside California. Businesses should review the details of a transaction before treating it as excluded or exempt. A $5 million rule for certain large purchases In some transactions, responsibility for paying the tax can shift from the retailer to the purchaser. The rule concerns a retailer’s aggregate gross receipts from digital products sold to the same purchaser that are transferred electronically or accessed remotely. For 2027 , the threshold is more than $5 million in that calendar year . Beginning January 1, 2028 , the test looks at whether those receipts exceeded $5 million in the current or preceding calendar year. When the rule applies, the purchaser may need a Use Tax Direct Payment Permit and may have to report and pay the tax directly to the California Department of Tax and Fee Administration (CDTFA). Location matters for local taxes For digital products transferred electronically or accessed remotely, the place of sale for local and district tax reporting is generally the customer’s address. The place of use is where the person accessing the product is located. That distinction matters when a company’s billing address and its software users are in different places. CDTFA explains the rules in its Tax Guide for Retailers and Purchasers of Digital Products . What sellers need to do California digital product sellers that are not already registered with CDTFA may need to obtain a seller’s permit , file sales and use tax returns, and report and pay tax on taxable retail sales. Out-of-state sellers that are engaged in business in California under Revenue and Taxation Code section 6203 may need a Certificate of Registration—Use Tax . They would collect and report use tax on covered sales to California consumers and pay it to CDTFA. Registration is available through CDTFA Online Services . The UBJ takeaway: Software sellers can use the months before January 2027 to review their products, customer locations, invoicing and registration needs. Buyers can review their software agreements and ask vendors how the new tax will appear on invoices. For the definitions, exemptions and reporting rules, start with CDTFA’s digital products tax guide
By Kim Anthony • September 24, 2026
Beverly Kuykendall helps businesses navigate complex markets, build stronger partnerships and turn ambitious ideas into workable plans. Some business leaders see a procurement requirement and stop at the obstacle. Beverly Kuykendall asks what it would take to move forward. Over decades in federal acquisition and commercialization, Kuykendall has helped organizations work through the demands of government contracting while keeping their commercial goals in view. Her career has included executive roles as President of Government Business, Chief Strategy Officer and President. In each, she has worked at the point where strategy must become something a team can actually execute. Today, Kuykendall advises mission-driven organizations and manufacturers seeking new routes to growth. For companies pursuing domestic production, that may mean beginning with practical steps such as packaging, labeling, kitting, light assembly or fulfillment. These staged solutions can help a manufacturer establish domestic capacity and enter a market while building toward a larger goal. She also helps manufacturers develop reseller and distribution programs with clear standards for selecting partners, onboarding them and measuring performance. The aim is to grow revenue while protecting the relationships and reputation a business has worked hard to build. Kuykendall’s strength lies in making complicated systems understandable and actionable. She sees how procurement rules, supply chains and commercial partnerships fit together—and where an organization can make its next move with confidence. For entrepreneurs and business leaders trying to enter a demanding market, that perspective matters. A complex path can still be a path. Kuykendall’s work helps organizations find it, prepare for it and take the next step.
By Kim Anthony • September 24, 2026
Felecia Fisher-Shamu has built a women-owned furniture manufacturing business whose work reaches from Los Angeles hotels to destinations around the world. Before Felecia Fisher-Shamu’s work appeared in luxury hotels and major entertainment venues, she was building relationships with the people who knew those spaces best: hotel engineering and housekeeping teams in Santa Monica and Los Angeles. She listened, learned what the work demanded and built a business around delivering it well. Today, Fisher-Shamu is CEO and co-founder of Vitality Casegoods, Restorations, and Furniture Manufacturing, Inc. In a competitive industry where women business owners have had to establish their place, she has earned a reputation for custom furnishings, furniture design and restoration. She has done it with creative vision, perseverance and a team of skilled craftspeople. Vitality’s work has reached properties in the United States, Anguilla, Saudi Arabia and Canada. Fisher-Shamu has contributed to sustainable projects with Google and ARIA in Las Vegas, as well as furnishings for major hotels and entertainment spaces. Her team’s work has also supported events associated with the NAACP Image Awards, the Daytime Emmys and Oscar celebrations, including a VIP gala honoring Black Panther costume designer Ruth E. Carter. Her passion for restoration gives the business another dimension. Vitality helped restore antiques from Paris for Lumière at the refurbished Fairmont Century Plaza in Los Angeles. Earlier in her career, Fisher-Shamu restored antiques for the Four Seasons Hotel Beverly Hills. She values the artistry in preserving a piece’s character as much as the skill required to create something new. Even during the pandemic, when the hospitality industry faced extraordinary disruption, Vitality continued to win work. Projects included SoFi Stadium’s Owners Club, Loews St. Louis Live! hotel and Circa Resort & Casino in Las Vegas. Fisher-Shamu’s story celebrates what a woman-owned business can build through talent, trusted relationships and the determination to keep going. Her furnishings may be found in celebrated spaces, but the deeper achievement is the enterprise she and her team have crafted along the way.
Show More